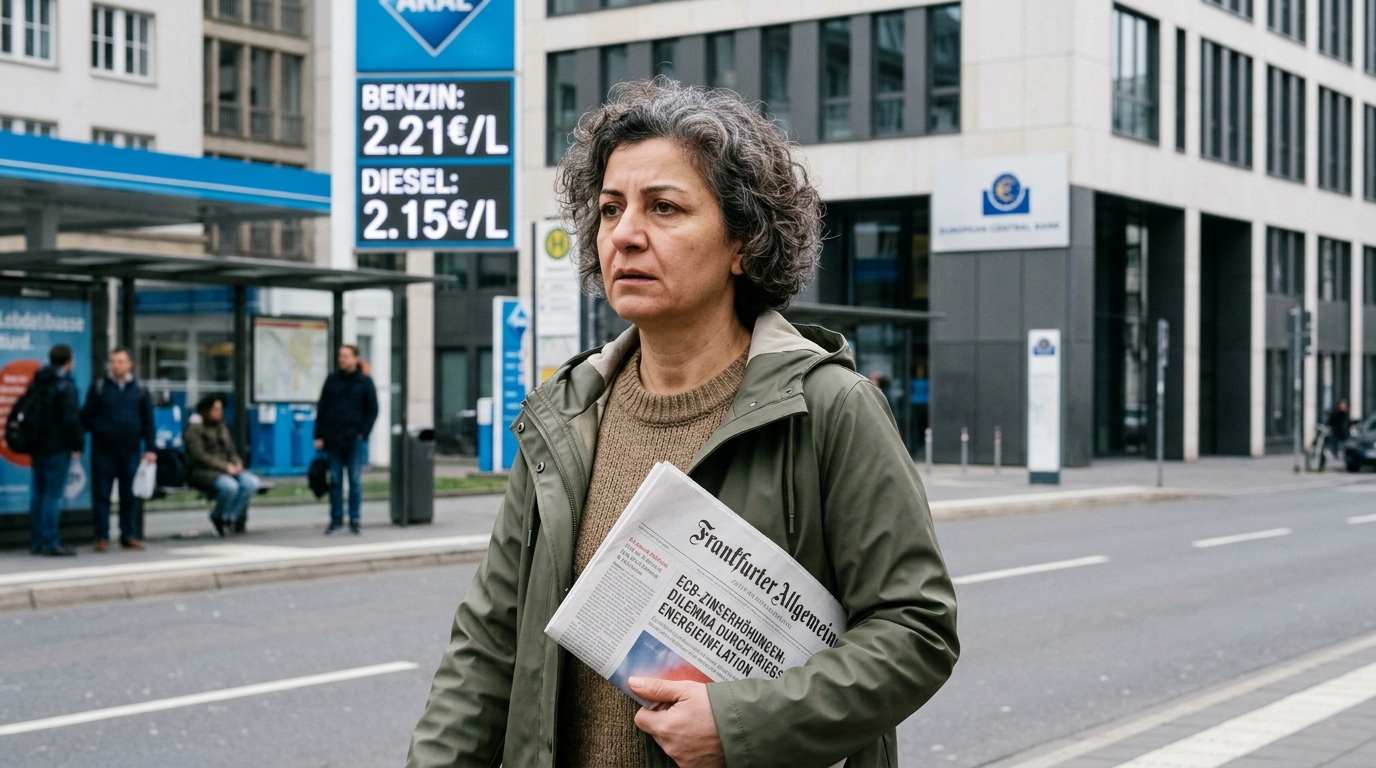
ECB Rate Hikes Highlight Growing Central Bank Dilemma over War-Induced Energy Inflation
The War-Driven Energy Shock: How the European Central Bank Got Caught in a Stagflationary Trap
The European Central Bank is walking an economic tightrope without a net: tightening monetary policy to extinguish supply-driven inflation risks pushing an already fragile bloc into deep stagflation.
On September 10, 2026, the European Central Bank (ECB) resumed its aggressive stance against inflation, delivering a 25 basis point rate hike that pushed the Deposit Facility rate to 2.50% and the Main Refinancing Operations rate to 2.65%. The Governing Council’s decision in Frankfurt laid bare a compounding existential dilemma facing modern monetary policymakers.
As geopolitical conflict in the Middle East disrupts global supply chains and crude prices breach $100 per barrel, energy-driven price hikes have pushed Eurozone headline inflation to a nearly three-year high of 3.3%.
Central banks are built to control domestic demand, but rate hikes cannot pump crude oil or secure natural gas transit routes. By raising borrowing costs to fight a war-induced energy shock, the ECB faces a punishing choice: risk let supply-driven inflation anchor into wage-price expectations, or squeeze bank lending so tightly that it chokes off an already fragile real economy.
The macroeconomic reality confronting the Eurozone reflects a textbook supply-side shock. Recent Eurostat figures show that energy inflation spiked to 14.3% in August 2026, up sharply from 10.3% in July. Yet, beneath this headline surge, core economic activity presents a stark contrast:
As detailed in the metrics above, core inflation—which strips out volatile energy and food—actually declined to 2.4% in August, while services inflation eased to 3.0%.
This divergence illustrates the central bank's structural limitation: monetary policy cannot fix broken energy routes. When a war disrupts oil and natural gas supplies, higher interest rates do not produce more energy. Instead, rate hikes work by making credit more expensive across the real economy, curbing consumer demand and business expansion until overall economic activity slows down enough to balance higher input costs.
Central bankers refer to this defensive tightening as paying for "inflation insurance". The core objective is to prevent temporary energy price increases from triggering "second-round effects"—a spiral where workers demand higher nominal wages to cover utility bills, and businesses pass those wage costs directly onto consumers.
However, with the ECB's updated projections foreseeing modest real GDP growth of just 0.9% for 2026, monetary tightening risks pushing marginal businesses into default and suppressing private investment. Morningstar
Looking forward, institutional forecasters and market analysts see three distinct paths for the Eurozone economy, depending on the duration of energy disruptions and the ECB's policy responses.
Potential Industry Scenarios
- Scenario 1: The Stagflation Spiral (Worst-Case Outlook)
- If Middle Eastern conflict drags on through late 2026, pushing natural gas and crude prices higher for a sustained period, energy-driven costs could seep into general core inflation. Under this scenario, market consensus suggests the ECB could feel compelled to push policy rates toward 3.00%. Such aggressive tightening during a period of zero growth could trigger corporate defaults in capital-intensive sectors like manufacturing, real estate, and heavy industrial processing. Anadolu Ajansı+ 1
- Scenario 2: The Insured Soft Landing (Baseline Sentiment)
- In the baseline scenario projected by ECB staff, headline inflation averages 3.0% in 2026 before cooling to 2.5% in 2027 and 2.1% in 2028. If energy disruptions prove temporary and wage growth remains contained, analysts expect the Governing Council to pause further rate adjustments after September 2026. This path would allow borrowing costs to stabilize while energy supply chains gradually adapt to new global trade flows. FXStreet
- Scenario 3: Fiscal Divergence and Green Structural Shifts
- A third potential outcome involves structural shifts in how Eurozone nations fund energy security. Continued energy price volatility could accelerate member states' investments in domestic renewable grids and liquefied natural gas (LNG) import infrastructure. However, funding these investments through public debt could widen fiscal imbalances between fiscal-heavy Northern European economies and debt-burdened Southern European nations, potentially testing the ECB's Transmission Protection Instrument (TPI).
The European Central Bank's current policy stance highlights a core reality of modern macroeconomic management: monetary tools are designed to manage demand, not repair supply lines.
Moving into late 2026 and early 2027, market participants and policy observers should track three key variables:
- Energy Futures and Commodity Trends: Whether crude oil holds above $100 per barrel or stabilizes will determine if headline inflation pressures persist into 2027. IndexBox
- Second-Round Wage Dynamics: Negotiated wage settlements across major Eurozone economies will signal whether workers are absorbing reduced purchasing power or passing energy costs back into core pricing.
- Credit Conditions and Lending Rates: Bank lending surveys will reveal whether the September rate hike is causing an unintended credit crunch for small-to-medium enterprises (SMEs) across the Eurozone.
Disclaimer: This article is strictly for informational, educational, and editorial purposes and does not constitute financial, legal, or investment advice.